A dental appointment should not come with a surprise financial conversation at the end. Dental insurance can reduce what you pay for many common services, but every plan has its own limits, rules, and coverage levels. Understanding those details before treatment begins helps you make decisions with more confidence, whether you are booking a cleaning for your child, replacing a damaged tooth, or considering a larger restorative plan.
For Scarborough families, working adults, and seniors, the most useful approach is to see insurance as one part of treatment planning, not the sole factor. Your oral health needs, comfort, timing, and long-term goals still matter. A dental team can help explain the clinical recommendation and provide an estimate based on the information available from your insurer.
How dental insurance usually works
Most employer-sponsored dental plans pay a percentage of eligible treatment costs up to a set annual maximum. The percentage may be higher for preventive care, such as examinations, hygiene cleanings, X-rays, and fluoride, and lower for more extensive work, such as crowns, bridges, dentures, or periodontal treatment.
A plan that says it covers 80 percent does not necessarily mean it will pay 80 percent of every dental bill. Coverage can be based on a fee guide, a specific procedure code, a frequency limit, or the plan’s annual maximum. If the clinic’s fee is higher than the amount recognized by the insurer, you may be responsible for the difference as well as the portion your plan does not cover.
Your insurance booklet or member portal is helpful, but it can be difficult to interpret. Terms such as deductible, co-payment, annual maximum, and reasonable and customary fee can make a straightforward question feel unnecessarily complicated. Asking the dental office to review your benefits before a larger procedure can bring much-needed clarity.
The services many plans cover
Coverage varies, but preventive services are often the most consistently supported part of a dental plan. This reflects a practical reality: regular care can identify decay, gum inflammation, cracked teeth, and other concerns before they require more involved treatment.
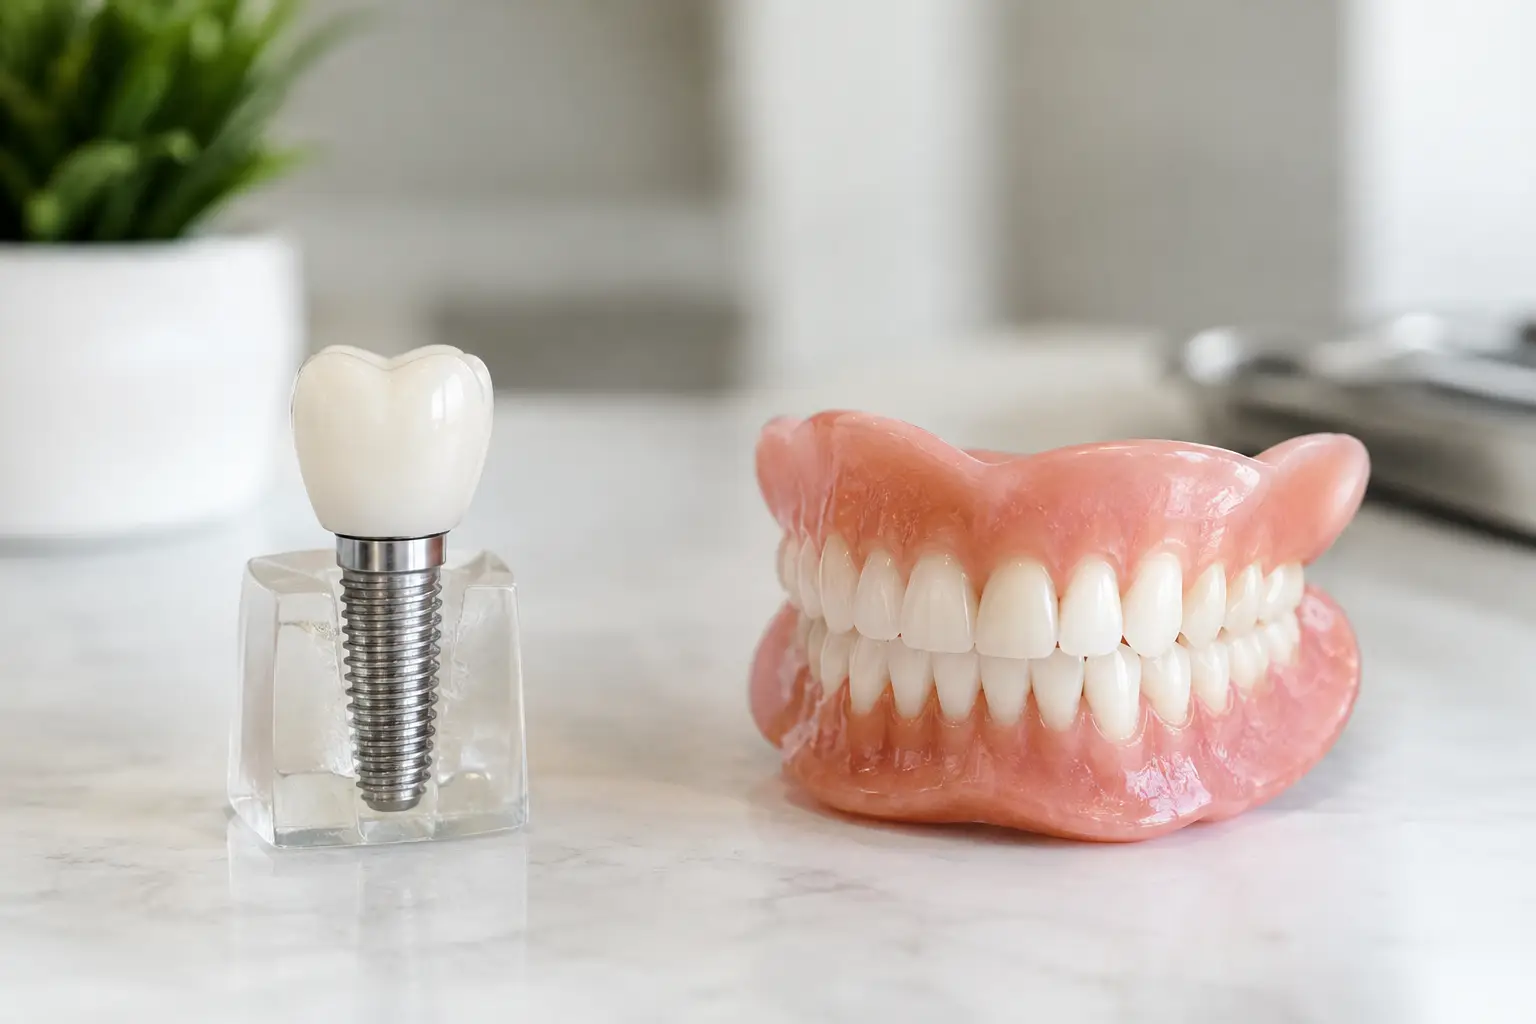
Basic restorative care commonly includes fillings, simple extractions, and some emergency treatment. Major restorative services may include crowns, bridges, dentures, root canal treatment, surgical extractions, and periodontal procedures. These categories are not universal. One plan may treat a particular procedure as basic care, while another classifies it as major care or excludes it altogether.
Orthodontic treatment, including Invisalign, is often covered under a separate lifetime maximum, if it is covered at all. Cosmetic services such as whitening and veneers are usually not included, even when they may improve the appearance of teeth. In some situations, a treatment can have both cosmetic and functional benefits. Your dentist can explain why a procedure is recommended, but the insurer makes the final coverage decision.
Frequency limits can affect routine visits
Many patients are surprised to learn that their plan may limit how often it pays for certain services. For example, a plan might cover an examination once every six, nine, or 12 months, or limit hygiene cleanings by calendar year or by a rolling period.
That does not mean more frequent care is unnecessary. Patients managing gum disease, heavy tartar buildup, dry mouth, orthodontic appliances, pregnancy-related gum changes, or a history of cavities may benefit from a recall schedule tailored to their needs. If your clinical needs fall outside your plan’s frequency rules, your dentist can explain the reason for the recommendation and the expected out-of-pocket cost.
Annual maximums matter more than many people realize
An annual maximum is the total amount your insurer will contribute during a benefit year. It is not the same as a spending limit for your dental care. Once the maximum is reached, you may still receive treatment, but you would pay the remaining cost yourself.
This is particularly relevant when several family members need care or when treatment involves multiple appointments. A crown, bridge, implant-supported restoration, denture, gum therapy, or oral surgery plan may use a meaningful portion of available benefits. Sometimes it makes sense to phase treatment across benefit years. Sometimes delaying care is not advisable because infection, pain, tooth movement, or further damage could make the issue more complex.
The right timing depends on your dental condition. A careful treatment plan should put health and function first, while also showing you practical options for scheduling care when appropriate.
Direct billing makes payment simpler, not coverage guaranteed
Direct billing means the dental office submits a claim to your insurance provider on your behalf. When the claim is processed, you typically pay the portion not covered by your plan. This can make visits easier to manage, especially for busy households, but it does not guarantee that every service will be paid by the insurer.
Claims may be adjusted because a maximum has already been used, a waiting period applies, a service is not eligible, or information on file is incomplete. For planned treatment with a significant cost, a predetermination can be requested. This is an estimate from the insurer outlining what it expects to pay before treatment is completed.
A predetermination is useful for planning, but it is not a promise of payment. Eligibility must generally still be active on the day of service, and the final claim remains subject to the insurer’s rules. Clear discussions before treatment help avoid confusion later.
Dental insurance and the Canadian Dental Care Plan
The Canadian Dental Care Plan, often called the CDCP, is not the same as private dental insurance. It is a federal program for eligible Canadian residents who do not have access to private dental coverage and meet its other requirements. It may help cover a range of oral health services, subject to eligibility, provider participation, co-payments, and any additional charges that may apply.
If you are eligible, bring your program information to the dental office before your visit. The team can help you understand the expected process and discuss any treatment costs that may not be fully covered. As with private plans, coverage should not be assumed for every procedure or situation.
Questions to ask before accepting a treatment plan
You do not need to become an insurance expert before seeing the dentist. It is reasonable to ask simple, direct questions: What treatment is recommended and why? Is there an alternative that is clinically appropriate? What portion may my plan cover? Will my annual maximum be affected? Can this treatment safely be phased, or should it be completed promptly?
For more extensive care, ask for a written treatment estimate. This gives you time to review the proposed care, contact your insurer if needed, and make arrangements that fit your budget. It also creates space for an honest conversation about your priorities, whether that means relieving pain quickly, restoring chewing ability, protecting a weakened tooth, or planning a longer-term smile improvement.
Choose care based on more than a benefit balance
Insurance benefits can be valuable, but they are designed around plan rules, not around the full picture of your oral health. A tooth with a large fracture may need attention even if your annual maximum has been reached. On the other hand, a stable concern that is not urgent may sometimes be scheduled thoughtfully around your benefits.
At Bright Smile Dental Clinic, treatment discussions are designed to be clear, respectful, and free from pressure. The goal is to help you understand your options, feel comfortable asking questions, and move forward with care that supports your health.
If you are unsure what your dental insurance will cover, bring your plan details to your next appointment. A clear estimate and a calm conversation can make it easier to protect your smile without guessing what comes next.